Multi-source funding
One payment, drawn from every balance a customer holds — selected or split at authorisation.
Let customers spend their wallet balances through the cards they already use.
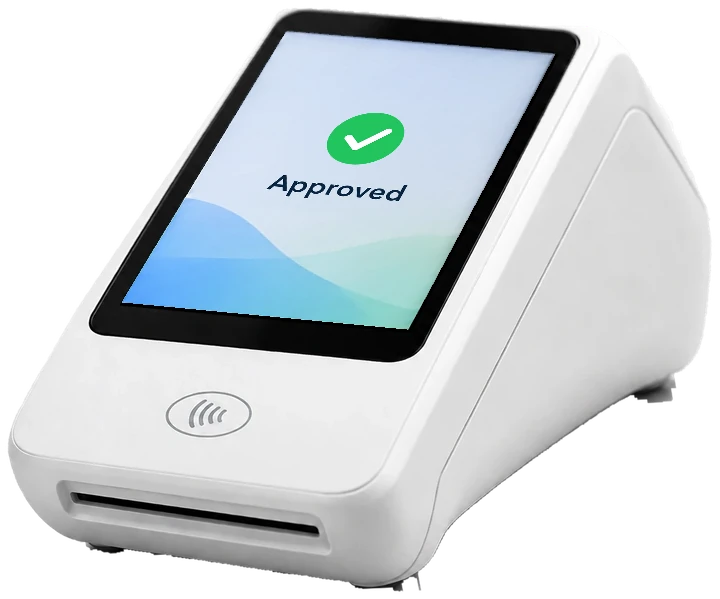
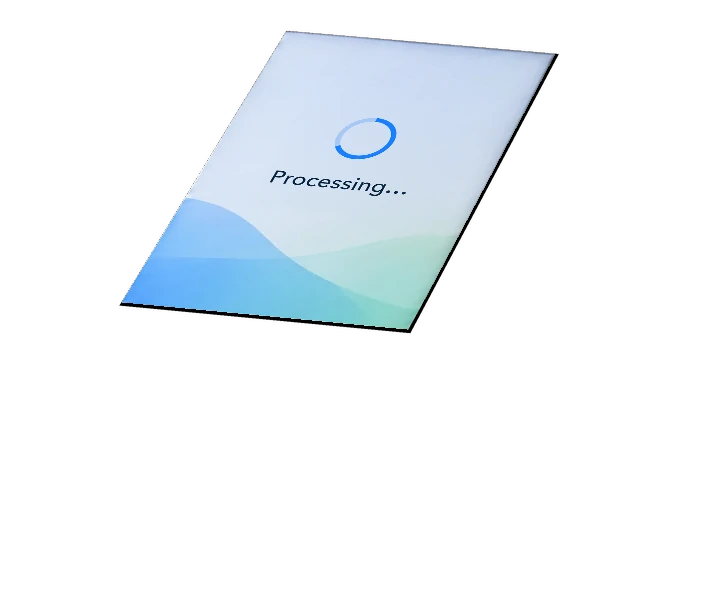
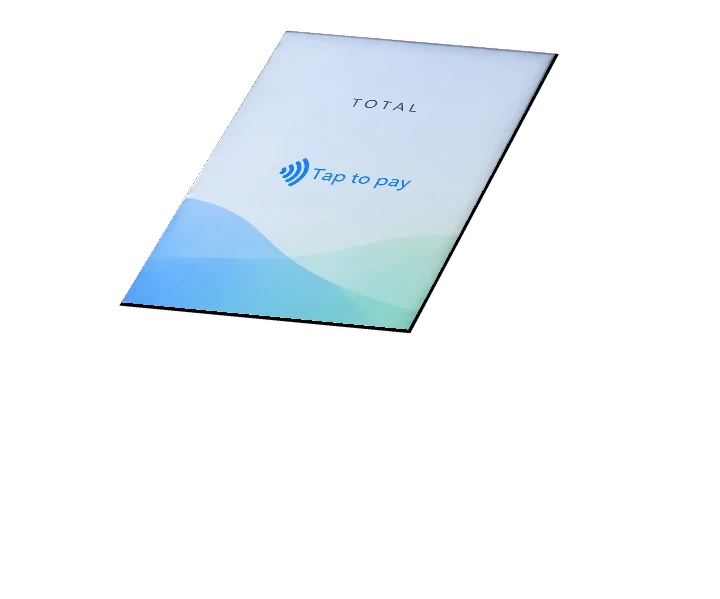
An animated illustration in two scenes. In store: the phone shows the card and a prompt to double-click the side button, is tilted to a countertop card terminal showing a 138 dollar 40 total, and the terminal approves the payment. Online: a web shop checkout asks the phone to confirm the same payment. Each of the three cards makes its own purchase: the first is funded from Bit plus the card, the second from PayBox plus the card, and the third from Bit, PayBox and PayPal plus the card. Online, the three purchases are flights with El Al, Arkia and Wizz Air. After each payment the phone shows how it was funded. Open any source for its date, amount, transaction number and remaining balance.
 Isracard
 powered by
Your card

Lifestyle
Groceries
Electronics
El Al · TLV → ATH
Arkia · TLV → LCA
Wizz Air · TLV → BUD
 Available balance
Part of a purchase
 Available balance
Part of a purchase
 Available balance
Part of a purchase
Part of a purchase
Showing: paying in store
Coming soon
For consumers
Use eligible wallet balances with the issuer card you already use.
Pick an eligible balance or set your preference.
Combine sources when supported by your issuer and wallets.
The same tap in store and familiar card checkout online.
Cross-border and recurring uses depend on issuer and funding-source support.
For wallets
Connect eligible wallet balances to the issuer card customers already use, so their money can travel further.
Let customers use eligible balances wherever the linked card is accepted.
Turn stored balance into everyday spending opportunities.
Keep your wallet experience and customer connection.
Expand utility through issuer-led distribution.
For issuers
Let cardholders pay from the wallet balances they already hold, through the card you already issued. No new card, no new rails.
Purchases once paid from wallets now run through your card.
Works with the cards and rails you already run.
Choose eligible wallets, limits and controls for every program.
Figures shown are illustrative.
All their wallets. One card.
Five things no single wallet, and no card programme, can do alone.
One payment, drawn from every balance a customer holds — selected or split at authorisation.
Nothing to install, sign or certify. It arrives as an ordinary card authorisation.
Wherever the networks are already taken — which is very nearly everywhere.
A local balance that travels. Cross-border spending with no transfer first.
Spending power grows with every connected balance — without extending more credit.
Contactless at any terminal. Same tap, same speed, no new hardware.
Every checkout that already takes cards. Nothing to integrate.
A domestic balance that travels. Acceptance follows the network, not the app.
The same tap. In every channel.
It behaves exactly like Apple Pay or Google Pay — because that is where it lives.
Figures shown are worked examples chosen to illustrate the mechanism, not measured results.
GSMA · World Bank · Visa and Mastercard published figures. Market context, not Accept² performance.
Five forces are converging to unlock billions in local wallet funds.
Hundreds of wallets. One set of rails.
Every wallet a customer holds becomes a single funding layer.
An existing card is made eligible. Nothing issued, nothing posted.
Accept² picks the balance, or splits across several. You approve.
Card payments funded from the wallet balances your customers already hold — one wallet or several, selected or split at authorisation.
The orchestration engine treats any balance as a funding source. These are next, not shipped.
We would rather be precise about what runs today than impressive about what doesn't.
| Traditional approach | vs. | Accept² approach |
|---|---|---|
| Merchant integration | ✕ | ✓No merchant changes |
| New consumer app or experience | ✕ | ✓No consumer changes |
| Single wallet or limited coverage | ✕ | ✓Any wallet |
| New network or infrastructure | ✕ | ✓Existing card rails |
| Generic PSP model | ✕ | ✓Issuer-first platform |
| Manual routing, limited intelligence | ✕ | ✓AI orchestration engine |
Never merchants. Nothing for them to install or sign.
Let's make it spendable — on your BIN, your rails, your terms.